Selling This Fall? A Major Appraisal Change Could Affect Your Closing Timeline

If you’re planning to sell before the end of the year, there’s a change happening behind the scenes of every financed sale that could catch you off guard: the entire residential appraisal system is being overhauled, and the mandatory deadline lands right in the middle of peak closing season. Here’s what’s changing, when it hits, and what it means for your sale.

What’s Actually Changing

Fannie Mae and Freddie Mac are retiring every legacy appraisal form — including the familiar 1004 used for most single-family homes — and replacing them all with a single, dynamic report called the Uniform Residential Appraisal Report, or URAR. Instead of a fixed template, the new report expands or contracts based on your property’s specific characteristics, and it’s submitted digitally as a structured data file rather than a static PDF.

This is the most significant change to residential appraisal reporting in over a decade, and it touches virtually every home sale that involves a mortgage — which means it very likely touches yours.

Key Dates You Should Know

  • Now through November 2, 2026: Lenders and appraisers are transitioning — some are further along than others.
  • August 6, 2026: The system began flagging appraisals still submitted in the old format, though it isn’t rejecting them yet.
  • November 2, 2026: The old format is retired for good. Any new appraisal must use the new report from this date forward.

If your home is under contract this fall, there’s a real chance your appraisal will be completed during this transition — which is exactly why it’s worth understanding now, not after it happens.

Why This Matters to You as a Seller

An appraisal that comes in on time and supports your sale price is one of the last hurdles between contract and closing. A few things are worth keeping in mind as this transition plays out:

  • Possible timeline adjustments: Some lenders and appraisers will still be adjusting to the new report format this fall, which can add a few days to an appraisal that would have moved faster a year ago.
  • More structured, more detailed data: The new report captures property information in a more granular, itemized way. Homes that are well-documented and well-presented are positioned to move through this process more smoothly.
  • Your agent’s readiness matters: An agent who understands the new format can anticipate questions, keep your closing on track, and flag potential issues before they become delays.

What You Can Do Now

You don’t need to become an expert in appraisal standards — that’s what your agent is for. But a few simple steps can help your sale move as smoothly as possible through this transition:

  • Have your home’s key details — recent upgrades, permits, square footage documentation — organized and ready to share.
  • Ask your agent directly how they’re preparing for the transition and what it could mean for your specific timeline.
  • Build a little flexibility into your closing expectations this fall, especially if you’re coordinating a sale with a purchase elsewhere.

The Bottom Line

This appraisal overhaul isn’t a reason to delay selling — it’s a reason to work with someone who’s already ahead of it. With the right preparation and the right team, your sale can move through this transition without missing a step.

If you’re thinking about listing this fall, let’s talk about what this means for your specific timeline before you go to market.
March Statistical Update

We have officially put both feet into a slow market, which is defined as 7 to 9 months of inventory.

Ilona Matteson - Slow Month

Here are the stats you need to know:

Market Metric

OBX Statistics

Total # of Properties for Sale

 917

Total # of Selling per Month

109

Months of remaining Inventory

8.4

# of New Listings each Month

213

If you are thinking about selling, remember back to the 2008 cycle.  This is the point where sellers thought prices would bounce back, so they wait.  Buyers felt prices may soften so they waited.  Who wins the waiting game in a declining market?

If you want to net the most, selling earlier in the cycle rather than later is how you will net more.  Contact me for a full analysis for your home.

2026 Real Estate Market Prediction

Ilona Matteson - 2026 Real Estate Market ForecastReal estate markets across the country are definitely starting to crack. The northeast is really the last holdout and there are signs of a beginning surge in inventory there. With slowing activity and rising inventory, it looks like the OBX could enter a buyers market by the second quarter of next year.
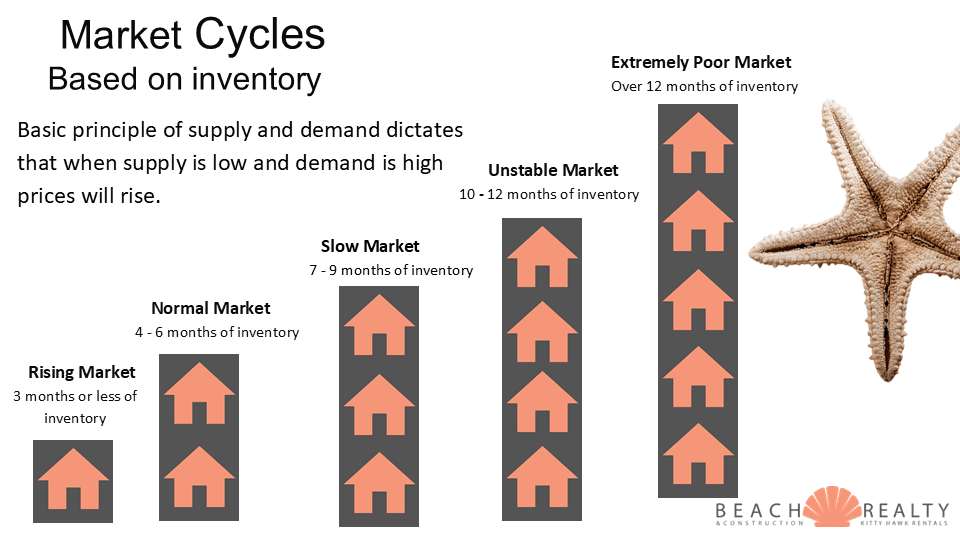
Right now, our absorption rate has us at the high end of a “normal market”. Just a small increase in inventory at today’s demand level will push us over the 6-month level and right into the next category; slow market, which will favor buyers more.

Most aren’t aware of the impending foreclosure tsunami that is coming in the second quarter of 2026. On October 1st, an FHA workout program that has been in place for the last 5 years got an overhaul. Borrowers have been issued loan modifications over and over.

New guidelines in place are:

  • Only one modification every 24 months
  • Must exhibit the ability to pay the new amount for 6 months
  • Cannot be behind on student loans

FHA is reporting one million borrowers are in default at least 30 days. With these new guidelines in place, that puts a lot of homeowners in jeopardy of being foreclosed. It’s a 90 day process
that started 3 weeks ago. By January, we could start seeing these new listings hitting the market across the country.

While I don’t expect it to have a huge impact on the Outer Banks, it will start to affect markets nearby. Being a resort area, we usually get the trickle-down effect, so expect to see possibly even slower sales next year, which will contribute to higher inventory, eventually translating

March OBX Market Report 2025

The impact of slowly rising inventory and decreased demand is starting to add up here on the Outer Banks.  Don’t get me wrong, homes in good condition, location and priced right are still selling very quickly.  We don’t have an overabundance of inventory, yet.  However, we are definitely seeing some markets shifting faster than others.

Here’s how each area breaks down:

Area Active Listings Sold/
Month
Month
 Supply
Corolla 161 10.6 15
Duck 33 3 11
S. Shores 32 5 6.4
Kitty Hawk 24 7 3.4
Kill Devil Hills 121 23 5.2
Nags Head 48 10 4.8


The relationship of inventory to number of homes sold per month gives us the absorption rate.  The absorption rate tells us how many months it would take to sell out the inventory at the current rate of sales.  That is a direct reflection of the “health” of a market, or describes what type of market we are in.  The chart below lists this out.  Based on this, you can see how each area is performing.

OBX Market Chart 2025

When shifting to a different market it’s common to see some areas performing differently than others.  If you consider the higher end markets will generally slow down first, and that is reflected here.

If you are thinking of selling in one of those markets, the time is now.

May OBX Market Update

May OBX Market UpdateIn a nutshell, the market here is changing…slowly…but surely.  These types of cycle shifts don’t happen all at once.  Fortunately, because I study the market every day, I can help you see it coming.  After all, you can get out of the way of what you don’t see!
Here are the basics we are watching:

Inventory

Total Everything – up 27% since January (currently over 1,000 listings)

           Homes, Single Family and Condos/Townhomes – up 24%

Activity

Absorption Rate has gone from 4.8 months to 5.5 months since January

This means it would take longer to sell the homes we currently have on the market.  Once this goes over 6 months, we enter a Slow Market

Price

53.5% of homes are still selling within 0-30 days, of those…

97% of asking price is what they are selling for

67% of homes are now selling under asking price

Basic supply and demand economics tell us that when supply is inching up, demand is inching down that prices will start to waiver.  How long will this current market last?  We just have to keep watching. We are noticing more price reductions coming in and fewer multiple offers.  This is an active situation.  Stay tuned for next month’s report!

If you have thought about buying or selling, let me know so we can plan your strategy.

First Quarter 2024 Comparison to First Quarter 2023

OBX Real Estate Market - Crystal Ball and upward graphWhat a difference a year makes!  Long story short, there are some BIG moves that are happening.  I’ve talked before about algorithmic decay.  This chart here is exactly that!  Little, by little, by little, then bang.  That’s how markets change.  Tale as old as time, song as old as rhyme, it’s almost as good as a crystal ball.
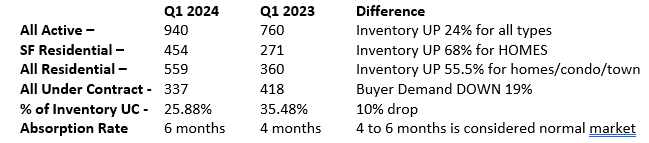
Anyone saying the real estate market on the Outer Banks is not changing is just not paying attention.

But, look here, and you decide:

Image of the differences between 2023 and 2024 in the OBX Real Estate Market

We are on the cusp of a price shift potentially starting this fall.  Here are the facts about our market:

  • Insurance costs are rising and coverage dropping
  • Interest rates are not changing any time soon
  • Rental income is back to pre-pandemic levels

If you are on the fence about selling your home, your window is closing before we start to see quantifiable price shifts.  Call me today to discuss the best strategy for selling in today’s changing market.

How NOT to set the listing price of your home.

151 Salt House Road, CorollaA lot of agents will do presentations on how they came up with a price for your home. It is a task that does require some skill. The challenge of course is getting the seller to agree to the pricing suggestions.
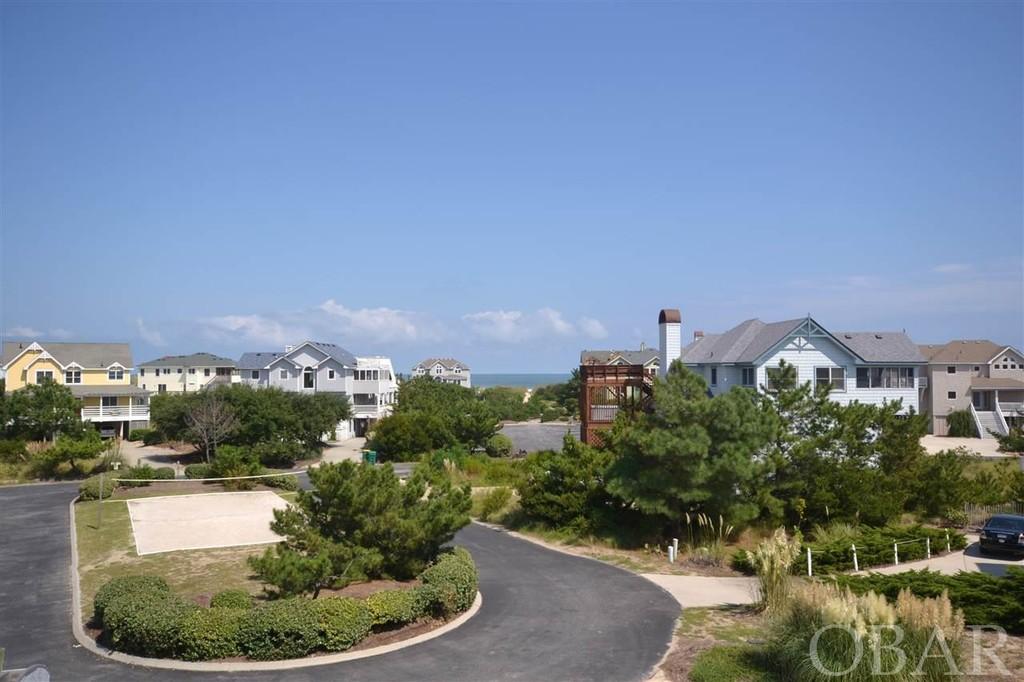
Many sellers come into the meeting with a general idea of what they want for the home, which is helpful. However, here are a few ideas on what NOT to do when you decide to sell your Outer Banks home in today’s market.

  • Tax Assessment Don’t confuse your county tax assessment with market value. Your tax assessment is for the purpose of assessing a tax amount to you for the purpose of revenue to the county. It doesn’t in any way suggest that’s what a buyer is willing to pay or a seller is willing to sell for. Most importantly the assessment on your home right now is 4 years old! On the Outer Banks they only re-assess every 8 years. Because it’s 4 years old, it also doesn’t take into consideration any improvements that have been done since the last assessment.
  • Old Appraisal Appraisals are only good for the day they are written. What? Yes, that’s correct. Considering that anything and everything could change tomorrow, an appraisal can only be valid for one day. If you have a year-old appraisal and want to base your price on some reflection of that, you might find yourself the highest bidder of your home. I mean I was a size 8 years ago, but that’s not exactly going in my dating profile for today!
  • Old Sales in the area – All agents have heard it… “Well, my neighbor sold last year for $30,000 more.” Markets never stay the same. It’s an ever-changing environment, which is why consulting with a good agent who studies home prices every day is the best way to get closest to current market value.
  • Recent Improvements – We’ve also all heard… “Well I have a new roof, HVAC and carpet. I want to ask $extra to cover those costs.” The fact that you’ve done these “maintenance” items is great. It shows you’ve taken care of the home. The problem is all houses need a roof, HVAC and carpet. In this market, that can make your home more saleable, not necessarily more valuable. Buyers expect the basic components to be in good condition already. What you can ask more for are upgrades. Changing vinyl to tile or carpet to hard wood, or laminate to granite are all upgrades.
  • Basing the price on your needs – We would all love to get the seller the most money possible. That’s part of our job. However, we can only sell the home for the true market value. Just because you NEED to get $50,000 at closing doesn’t mean it’s going to happen. You have to consider all the current factors in your marketplace and if those point to a lower price, you needing that money will not cause a buyer to pay it if the value isn’t there. You may need to adjust your plans based on what’s realistically going to come out of the sale of your home. These are hard conversations, but a good agent will not be afraid to spell out the truth.
  • Stuck on a previous market value –The last few years have been monumental. It was a fast- rising market and prices skyrocketed. Now we are in a more “normal” market. Prices aren’t rising or falling at a tangible rate just yet. Mostly because inventory is still too low. However, don’t get complacent. Markets ALWAYS cycle. What goes up, must come down. I predict this fall pricing will look differently than it does right now. So, pay attention to CURRENT trends and not what happened the last year or two.
  • Focus only on Price – So often I hear, “I don’t have to sell, I’ll just wait if I have to sell at that price.” Selling a home is based on a LOT of decisions, not just the price for it. No one wakes up and turns to their spouse and says “Honey, the house is worth $X, we have to sell it.” Selling is based upon life changes, new needs, maintenance costs, jobs, marriages and so many more things that are related to the way we live our lives. It’s sometimes concerning when I see a seller refuse to sell based solely on the price. That means they are putting that dollar value above the benefits selling the home can bring to the family. Don’t let the emotional response to the price create a “wish I would have” moment.

Now that we’ve covered what NOT to do, if you need help pricing your Outer Banks home for a prime spot in our market today, certainly let me know how I can assist you!

The “Raw Truth” about the OBX market right now.

It’s no secret the real estate market is in very bad shape right now.  And in an effort to be as up-front as possible about the pros and cons, I wanted to create this quick list of the main things to consider before buying or selling.
One of the biggest questions I get as an agent is around timing.  When is the right time to buy or to sell?  Truthfully, there is not a one-size-fits-all answer to this.  The best time is when you want to.  Rarely do we have clients who HAVE to buy or sell out of some distress.  That’s just not the norm.  So, does it make sense for YOU to buy or sell right now?  Let’s look at the raw truth.

  1. Outer Banks homes have the ability to generate quite a nice rental income. If you want to insure your long-term capability to own the home, only look at homes with income that is enough to cover the mortgage.  If it’s not going to cover at least that part, it may not be the right house for you.
  2. OBX home purchases are primarily a lifestyle choice. It’s not the norm to make bank on rental income, so only buy a home you know you will get a lot of personal use from.  If it’s not really ideal for your family, you won’t use it.  That time spent is priceless.  Be sure it fits your future family, too.
  3. With banks failing as what seems to be a regular occurrence now, real estate is an actual tangible asset. While the prices do fluctuate, it will never go to zero.  The inflationary dollar is in real trouble.  Why not park some cash in real estate, especially with passive income and personal use on the table?
  4. However, real estate appreciation or value is NOT capable of instant liquidity. Unless you consider 30 days instant.  Pulling liquidity out of real estate takes some financial investment and, most importantly, time.  If you need liquid cash fast, this is not the right investment.
  5. MAINTENANCE IS MANDATORY. Let me say that again.    Do not become one of those lax owners who collects the money and does nothing to the house for 20 years.  It will only cost more later.  The environment here is harsh.  Annual maintenance to keep the home in top condition is expensive.  Be prepared for that, or just buy raw land instead.
  6. While we benefit from low taxes here, insurance is most definitely on the rise! It may soon be unaffordable for many.  And, there is talk of no longer offering coverage for natural disasters.  I can’t imagine they get away with that, but be aware it’s being talked about. To be properly insured could be pushing $15,000 for many homes these days.  It’s nothing to take lightly.  Make sure you aren’t currently under-insured.  Construction costs for a new build START at $300/sq.ft. now!  (I hope you were sitting when you read that)
  7. Interest rates aren’t forever; you can refinance! Granted, you will need equity in the home to do that, so be aware it does come with some risk if that is your plan.  You will need to refinance before the market price eats up your 20% down payment, or it will require more cash to make it happen.
  8. As a Long-term investment plan, real estate is actually very low risk – high reward. Even if someone bought in the last boom of 2005, just 16 years later, even they would have made a handsome profit.  Not to mention 15 or 20 years of someone else paying your mortgage…all that equity for you to capitalize on at the end.

If you would like to discuss your specific circumstances and find out the best timing to either buy or sell, just contact me and we will go through everything you need to know!

August Market Update 2023

August on the Outer Banks

We are closely watching the main stats on supply (up 33% since January) and demand (down 44% since January).  Part of that is watching more specific pockets of activity to glean a closer insight into future trends.  One of those trends I’ve noticed in my near 30 year career is that of high-end home sales.

Take a look at the numbers for Duck and Corolla.

Homes sold $2M and over:

2019 –              6

2020 –              26

2021 –              64

2022 –              51

2023 –              17 YTD  (Likely on track for 27 total)

    • Even if we end up at 27 sold, that will be a decline of 47% year over year.
    • Number of price reductions to get homes sold is going up; 60% of properties sold are under list price, compared to 51% last year.
    • Median days on market for the high-end sales has gone from 21 days to 93 days year over year.
    • There are currently 30 homes for sale in Duck and Corolla $2M and over. With basically 2.4 buyers a month this is over a year worth of inventory.

With interest rates rising, insurance costs rising, rents stabilizing to pre-pandemic times, it’s really clear that a shift in pricing has to take place.  The timing of this is what’s left to be seen.  This strange anomaly of still very low inventory (although is starting to slowly climb) is keeping us stuck in limbo.

If you’re thinking about selling, let’s talk about what your home’s value may look like in this market.

Beach Realty and Construction’s Agent of the Year for 2022

Beach Realty and Construction’s Agent of the year for 2022

Congratulations to Beach Realty and Construction’s Agent of the year for 2022, Ilona Matteson! This is Ilona’s third year in a row earning the title of Agent of the Year! In the year 2012 Ilona first achieved this award and has gone on to earn the title 5 more times! We are proud to have Ilona as a leader, trainer, and valued agent on our team.

Ilona Matteson brings a wealth of experience and knowledge to the sales team at Beach Realty & Construction. As a former sales manager for Beach Realty and a former coach for the nationally acclaimed Mike Ferry Organization, Ilona knows the real estate business inside and out. In 2004, she was selected for the annual 30 Under 30 feature for Realtor Magazine and was also a licensed instructor employed by the North Carolina Academy of Real Estate. Ilona has a thorough understanding of market conditions and works diligently for her clients.

Be sure to call Ilona Matteson for all your Real Estate Needs!