A Proposed Rate Hike Could Raise Your Cost of Living

Here’s How to Have Your Say (Including a Hearing in Manteo)

Property taxes are up. Insurance premiums are up. Groceries, healthcare, and everyday household costs keep climbing. Now Dominion Energy North Carolina wants to raise electric rates too — and residential customers are being asked to shoulder a bigger increase than anyone else. Here’s what’s happening, the real numbers, and exactly how to weigh in — including a public hearing right here in Dare County.

What’s Happening

On April 30, 2026, Virginia Electric and Power Company, doing business as Dominion Energy North Carolina (DENC), filed an application with the North Carolina Utilities Commission (NCUC) requesting authority to raise the rates it charges for retail electric service — docketed as Docket No. E-22, Sub 765. Because Dominion operates as a regulated monopoly, it can’t simply set its own prices: it has to prove to the Commission that its requested rates are just, reasonable, and in the public interest.

The Numbers

DENC is seeking a total revenue increase of approximately $37 million, an 11.99% increase over current base rates. But that average hides an important detail: residential customers aren’t being asked to shoulder an average increase — they’re being asked to shoulder the largest one of any customer class.

  • Residential customers: a 15.42% increase — $25.87 million of the total $36.8 million requested increase
  • Overall system-wide average: 99%
  • Outdoor/streetlight customers: 75%, the single largest percentage increase of any class

In other words, households are being asked to absorb a disproportionate share of this increase compared to large commercial and industrial customers. And there’s more to watch for: DENC has indicated it plans a follow-up filing in September 2026 with new expenditures that will likely push the requested rates even higher than what’s reflected here.

What DENC Says the Money Is For

According to the filing, DENC attributes the request to investments made since its last rate case in 2024, including:

  • Nuclear fleet investments to maintain safe, reliable, and efficient operation
  • Fossil fleet investments for continued reliability and to uprate certain natural gas units
  • Renewable energy and battery storage, including hydro, biomass, solar, and offshore wind
  • Transmission and distribution infrastructure expansion across North Carolina

DENC is also seeking a separate annual rider to recover costs tied to the Coastal Virginia Offshore Wind (CVOW) Commercial Project — a cost that would come in addition to the base rate increase above.

Key Dates to Know

  • December 1, 2026: DENC’s proposed rates take effect on a temporary basis, subject to refund, while the Commission investigates.
  • January / February 2027: The Commission expects to make its final determination on the requested increase.
  • On or around March 1, 2027: Whatever rates the Commission approves are expected to take effect permanently.

In other words, rates don’t change overnight — but the window to be heard is open now, well before the final decision is made.

Why This Matters — Especially for Homeowners

Electricity isn’t a discretionary expense. It’s what keeps the heat and air conditioning running, the refrigerator cold, and the lights on — a basic cost of owning or renting a home, not an optional line item. A 15.42% increase for residential customers, layered on top of already-elevated property taxes, insurance premiums, and everyday household expenses, adds real pressure to family budgets, retirees on fixed incomes, and small businesses alike.

For anyone thinking about buying, monthly utility costs are part of the real, ongoing cost of homeownership — the number that factors into what a family can comfortably afford well after closing day. For current homeowners, it’s one more rising cost stacked on top of several others this year, and residential customers are being asked to absorb more of it than most.

How to Make Your Voice Heard

The Commission has laid out two ways to participate — you don’t have to do both, and neither is required, but either one puts your voice on the record.

Option A: Submit a written comment (about two minutes)

  1. Go to gov/contactus.html and open the online comment form.
  2. Copy and paste a consumer statement like the one below into the form, and include the docket number, E-22, Sub 765, at the top.
  3. Add your name and your city in North Carolina, then submit.

Option B: Testify at a public hearing

Your testimony becomes part of the official evidence the Commission considers. Four hearings are scheduled, all at 7:00 p.m.:

Date & Time Location Town / City
Mon, Sept 28, 2026 Halifax County Courthouse, District Courtroom, 357 Ferrell Lane Halifax, NC 27839
Mon, Oct 5, 2026 Remote via WebEx — register by 5:00 p.m., Sept 25, 2026 (first 20 registrants only) Virtual
Tue, Oct 13, 2026 Dare County Commissioners’ Meeting Room, 962 Marshall C Collins Drive Manteo, NC 27954
Wed, Oct 14, 2026 Martin County Courthouse, 305 East Main Street Williamston, NC 27892

For anyone local to the Outer Banks, the Manteo hearing on October 13 is the closest option to home. If you’d rather testify remotely, the WebEx registration deadline is 5:00 p.m. on September 25, 2026 — that hearing is canceled entirely if no one registers by then.

I respectfully urge the North Carolina Utilities Commission to reject any excessive rate increase requested by Dominion Energy North Carolina in Docket No. E-22, Sub 765. While reliable electric service is essential, any increase must be carefully justified and balanced against the significant financial challenges already facing North Carolina households.

Residents across the state are experiencing continued increases in the cost of living, including higher property taxes, homeowners insurance premiums, food costs, healthcare expenses, housing costs, and other essential household necessities. Electricity is not a discretionary expense; it is a basic necessity that families depend on for heating, cooling, food preservation, medical needs, and daily living. A substantial rate increase would place additional strain on working families, retirees on fixed incomes, low-income households, and small businesses that are already struggling to absorb rising costs.

As a regulated monopoly, Dominion Energy North Carolina has an obligation to demonstrate that any requested increase is prudent, necessary, and supported by reasonable cost management efforts. The Commission should carefully scrutinize the application to ensure that customers are not being asked to bear costs that could be reduced through operational efficiencies or other alternatives.

At a time when North Carolinians are facing unprecedented increases in property taxes, homeowners insurance, automobile insurance, food, housing, healthcare, and other essential costs, now is not the time to approve a substantial electric rate increase. The Commission should place consumer affordability at the forefront of its decision-making process.

Respectfully submitted,

[Your Name]

[City, North Carolina]

The Bottom Line

Most rising costs land on your bill with no warning and no way to push back. This one comes with an actual opportunity to be heard before the decision is made. If affordability matters to you — whether you’re a homeowner, a buyer planning ahead, or just someone watching your budget stretch further each year — it’s worth a few minutes to submit a comment or show up in Manteo on October 13.

A quick note if you plan to attend in person: some local courthouses don’t allow electronic devices inside, so bring a printed copy of any prepared statement.

Share this with neighbors, friends, and family across North Carolina. The more voices the Commission hears from, the more it understands what these increases actually mean for the households living with them.
Selling This Fall? A Major Appraisal Change Could Affect Your Closing Timeline

If you’re planning to sell before the end of the year, there’s a change happening behind the scenes of every financed sale that could catch you off guard: the entire residential appraisal system is being overhauled, and the mandatory deadline lands right in the middle of peak closing season. Here’s what’s changing, when it hits, and what it means for your sale.
What’s Actually Changing

Fannie Mae and Freddie Mac are retiring every legacy appraisal form — including the familiar 1004 used for most single-family homes — and replacing them all with a single, dynamic report called the Uniform Residential Appraisal Report, or URAR. Instead of a fixed template, the new report expands or contracts based on your property’s specific characteristics, and it’s submitted digitally as a structured data file rather than a static PDF.

This is the most significant change to residential appraisal reporting in over a decade, and it touches virtually every home sale that involves a mortgage — which means it very likely touches yours.

Key Dates You Should Know

  • Now through November 2, 2026: Lenders and appraisers are transitioning — some are further along than others.
  • August 6, 2026: The system began flagging appraisals still submitted in the old format, though it isn’t rejecting them yet.
  • November 2, 2026: The old format is retired for good. Any new appraisal must use the new report from this date forward.

If your home is under contract this fall, there’s a real chance your appraisal will be completed during this transition — which is exactly why it’s worth understanding now, not after it happens.

Why This Matters to You as a Seller

An appraisal that comes in on time and supports your sale price is one of the last hurdles between contract and closing. A few things are worth keeping in mind as this transition plays out:

  • Possible timeline adjustments: Some lenders and appraisers will still be adjusting to the new report format this fall, which can add a few days to an appraisal that would have moved faster a year ago.
  • More structured, more detailed data: The new report captures property information in a more granular, itemized way. Homes that are well-documented and well-presented are positioned to move through this process more smoothly.
  • Your agent’s readiness matters: An agent who understands the new format can anticipate questions, keep your closing on track, and flag potential issues before they become delays.

What You Can Do Now

You don’t need to become an expert in appraisal standards — that’s what your agent is for. But a few simple steps can help your sale move as smoothly as possible through this transition:

  • Have your home’s key details — recent upgrades, permits, square footage documentation — organized and ready to share.
  • Ask your agent directly how they’re preparing for the transition and what it could mean for your specific timeline.
  • Build a little flexibility into your closing expectations this fall, especially if you’re coordinating a sale with a purchase elsewhere.

The Bottom Line

This appraisal overhaul isn’t a reason to delay selling — it’s a reason to work with someone who’s already ahead of it. With the right preparation and the right team, your sale can move through this transition without missing a step.

If you’re thinking about listing this fall, let’s talk about what this means for your specific timeline before you go to market.

Outer Banks Home Prices Just Fell $182,000

Here’s What That Actually Means

If you’ve glanced at the Outer Banks market lately and felt like something shifted, you’re not imagining it. The average sold price has dropped from $801,000 at the end of April to $619,000 this month — a swing big enough to make any buyer, seller, or fellow agent stop and ask what’s really going on.

Here’s the full picture, numbers included.

Prices Are Down — But Not as Much as the Headline Number Suggests

The average sold price fell from $801,000 at the end of April to $619,000 this month. That’s a dramatic-looking drop, and it’s real — but the median tells a steadier story: it moved from $612,500 to $559,000, or 8.7%. The average is more easily skewed by a handful of high-end sales, so when it falls faster than the median, it usually means fewer luxury properties changed hands recently — not that every home on the market lost a fifth of its value.

Bottom line for clients: typical homes are selling for somewhat less than they were in the spring, but the market hasn’t collapsed — the mix of what’s selling has simply shifted toward more moderately priced homes.

Buyers Are Negotiating — And Winning

In August, 82% of sales closed under asking price, well above the year-to-date average of 77.5%. Sellers who priced aggressively this spring are increasingly meeting buyers who expect, and are getting, room to negotiate. If a listing isn’t priced with today’s market in mind, buyers are demonstrating they’re willing to walk rather than pay full ask.

Bottom line for clients: this is a buyer’s market when it comes to negotiating power — sellers need a sharper pricing strategy from day one, and buyers have real leverage to use.

Inventory Is Loosening Up

Absorption rate measures how long it would take to sell through current inventory at the current sales pace — the higher the number, the more time buyers have and the less pressure sellers can apply.

  • All properties (Outer Banks): 7.4 months of inventory
  • Residential only: 6.1 months of inventory

Both numbers sit at or above the 6-month mark that typically separates a seller’s market from a buyer’s market. Residential inventory is moving a bit faster than the overall property pool (which includes condos, townhomes, and other property types combined), but neither segment is running lean anymore.

What This Means Going Forward

Between softening prices, a high rate of below-ask sales, and rising absorption, the data points in one direction: the Outer Banks has shifted into a more balanced, buyer-friendly market. That’s not bad news — it just means the strategy has to change. Sellers who price realistically and show well are still finding buyers. Buyers who’ve been priced out over the past few years finally have room to negotiate.

Whether you’re buying, selling, or just keeping an eye on the market, now is the time to have a real conversation about strategy — the numbers say the old playbook doesn’t apply anymore.

Mid-Year Review of OBX Stats

July Market Update

2025 2026
Total homes sold 458 443
Median Price $725,250 $740,000
Median Days  37 34


Corolla 106 117
Duck 40 42
SShores 48 41
Kitty Hawk 42 56
KDH 129 114
Nags Head 93 73

As you can see, not much has changed year over year. Inventory is remaining low, keeping prices steady.  Activity seems to be hovering around the same as well.  With the days on market at just over a month, it’s pretty easy to tell if your home is priced according to the market.

If you are sitting on equity in your home and want to see what the market value is, contact me for a full analysis.

OBX April Market Update

Nothing tells the story of a market better or more accurately than inventory.  This goes back to the basic principle of supply and demand.  Inventory levels, or absorption rate, predict the health of a market by comparing what’s on the market, what’s selling, and how long it would take to sell off the current inventory.  While most markets show a 5-month supply, indicating a normal market, what’s alarming is that the rate of new listings coming on in most areas is double the number coming off.

Eventually, that leads to a backup of supply.  Unless activity picks up to match the new inventory, most of these areas will be in a “slow market” before the end of the 2nd quarter.

Here’s what each area looks like:

Corolla Duck Southern Shores
Active – 159 Active – 25 Active – 21
Sold/month – 17.6 Sold/month – 5 Sold/month – 4.6
Months/Invent  – 9 Months/Invent – 5 Months/Invent – 5
New/month – 40 New/month – 15 New/month – 8
Kitty Hawk KDH Colington
Active -32 Active -86 Active –  35
Sold/month – 6.3 Sold/month -17 Sold/month -7
Months/Invent  – 5 Months/Invent  – 5 Months/Invent  – 5
New/month – 12 New/month – 27 New/month – 14
Nags Head
Active -74
Sold/month – 6.6
Months/Invent  – 11
New/month – 33

You are watching in real time a market shift from normal – buyer’s market.  Inventory is building, and buyer demand is slowing.  What’s even more telling is that the homes still selling quickly are the ones with complete updating.  If you are thinking of selling, you WILL need to plan ahead and get the right strategy in place in order to have a successful close.

Let me know how I can help.

March Statistical Update

We have officially put both feet into a slow market, which is defined as 7 to 9 months of inventory.

Ilona Matteson - Slow Month

Here are the stats you need to know:

Market Metric

OBX Statistics

Total # of Properties for Sale

 917

Total # of Selling per Month

109

Months of remaining Inventory

8.4

# of New Listings each Month

213

If you are thinking about selling, remember back to the 2008 cycle.  This is the point where sellers thought prices would bounce back, so they wait.  Buyers felt prices may soften so they waited.  Who wins the waiting game in a declining market?

If you want to net the most, selling earlier in the cycle rather than later is how you will net more.  Contact me for a full analysis for your home.

2025 Recap

If we look at a recap of 2025, the story is small changes from 2024.

Take a look:

Category 1 – Closing Price

2024

2025

Closed Full Price

20.94%

19.5%

Down

Over List Price

11.38%

9.36%

Down

Under List Price

67.88%

71.14%

Up

Total # Sold

2,206

2,190

Down

Either sellers are getting more aggressive on pricing, or buyers are offering less overall.

Category 2 – Basic Activity comparing January 2025 to January 2026

2025

2026

Status to U/C

179

181

Median DOM

40

54

New Listings

328

297

Price Changes

190

196

Total Sold

162

153

Median DOM

65

38

Category 3 – Current Market Absorption comparing January 2025 to January 2026

2025

2026

Active Homes

568

529

Under Contract

246

256

% of INV U/C

18%

19%

Absorption Rate

5.9

5.5

If you would like to set an appointment to detail a plan for accomplishing your 2026 OBX real estate goals, let me know, and we will set something up!

Why Selling Now Makes the Smartest Financial Sense

Every Cycle Tells the Same Story

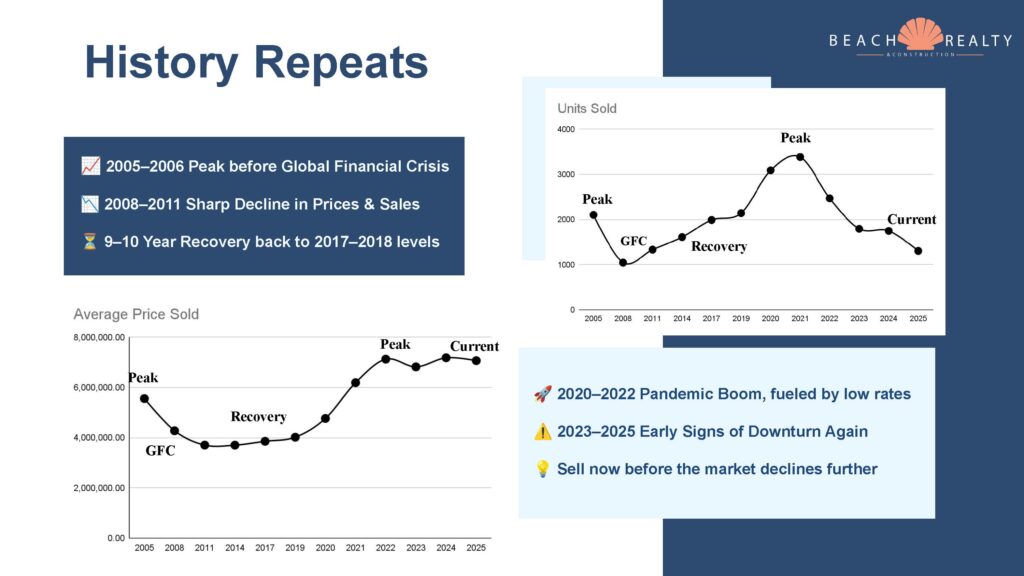
In 2005 and 2006, we hit a major peak before the 2008 financial crisis struck. From 2008 through 2011, prices and sales activity fell sharply — and it took nearly a full decade to recover. Then came another boom from 2020 to 2022, fueled by record-low interest rates and intense buyer demand. Now, as we move through 2023–2025, we’re beginning to see familiar signs: softening demand, rising inventory, and leveling prices.

That pattern should sound familiar — because it’s the start of the next cycle.

The Psychology of the Market

We all remember that subprime mortgages triggered the 2008 crash. What’s happening now is broader — economists call it the “everything bubble.” Once bubbles begin to deflate, it typically takes four to five years to reach the bottom. The reason? Seller denial. Sellers hold out, convinced prices will bounce back, while buyers wait for better deals. In a resort market like ours, where neither side must move, both dig in.

Sellers say, “I’ll just keep it for now.”       Buyers say, “I’ll wait until prices drop.”
And who wins the waiting game? Buyers do — every time.

Key Takeaways

• The last downturn took nearly a decade to recover.
• We’re seeing early signs of another correction.
• Selling before the decline accelerates protects your equity.
• Waiting could mean competing with more sellers at lower prices — and watching your gains fade over
years, not months.

Absorption Rate

Absorption rate is a key real estate metric that shows how quickly available homes are selling in a specific market.
It’s calculated by taking the number of homes sold and comparing it to the total number of homes currently for sale.

How to use the number:

  • 0–3 months → 🔥 Seller’s Market (homes selling quickly)
  • 4–6 months → ⚖️ Balanced Market
  • 7+ months → 🧊 Buyer’s Market (homes sitting longer)

See how each town compares here: 

Corolla Duck S. Shores Kitty Hawk KDH Nags Head
Active –  145 32 18 30 100 62
Sold/Month – 17.8 7.3 7.8 7.1 21.8 14.9
Abspt Rate –
in months
8
months
5
months
2.5
months
4
months
4.7
months
4
months
*NL/Month  37 11 3 9 42 13

(*NL/Month = New listings each month)

We know a market is shifting when the Absorption rate goes over 6 AND the number of new listings each month far exceeds the number selling each month.  We are watching Corolla and Kill Devil Hills closely right now.


2026 Real Estate Market Prediction

Ilona Matteson - 2026 Real Estate Market ForecastReal estate markets across the country are definitely starting to crack. The northeast is really the last holdout and there are signs of a beginning surge in inventory there. With slowing activity and rising inventory, it looks like the OBX could enter a buyers market by the second quarter of next year.
Right now, our absorption rate has us at the high end of a “normal market”. Just a small increase in inventory at today’s demand level will push us over the 6-month level and right into the next category; slow market, which will favor buyers more.

Most aren’t aware of the impending foreclosure tsunami that is coming in the second quarter of 2026. On October 1st, an FHA workout program that has been in place for the last 5 years got an overhaul. Borrowers have been issued loan modifications over and over.

New guidelines in place are:

  • Only one modification every 24 months
  • Must exhibit the ability to pay the new amount for 6 months
  • Cannot be behind on student loans

FHA is reporting one million borrowers are in default at least 30 days. With these new guidelines in place, that puts a lot of homeowners in jeopardy of being foreclosed. It’s a 90 day process
that started 3 weeks ago. By January, we could start seeing these new listings hitting the market across the country.

While I don’t expect it to have a huge impact on the Outer Banks, it will start to affect markets nearby. Being a resort area, we usually get the trickle-down effect, so expect to see possibly even slower sales next year, which will contribute to higher inventory, eventually translating